Staff gifts
A gift to staff is tax-free for the employee when the whole staff receives it, it is not money, and the total value of minor gifts is no more than 100 euros a year. Gifts for milestone occasions have their own, higher value limit. The company can deduct the cost of staff gifts, but it cannot deduct the VAT on them.
This page has staff gifts with a logo for different occasions: milestone occasions, Christmas, a welcome pack for a new employee, and a summer party or recreation day. The price on the product page includes a one-colour print in one position.
Which gifts are tax-free for the employee
According to the Finnish Tax Administration's guidance on employee benefits in taxation (Henkilökuntaedut verotuksessa), a minor gift is tax-free for the employee when these conditions are met:
- the gift is given to the whole staff
- the gift is not money or a payment comparable to money
- the total value of minor gifts is no more than 100 euros a year.
In the guidance, a minor gift means mainly a small Christmas gift to the whole staff. The gift can be an item, an admission ticket or a service chosen by the employer. The employee can also choose the gift from options that the employer has decided in advance. The whole staff also includes fixed-term and part-time employees.
A gift card is tax-free only when it is given to a named employee, its use is limited to an item or service obtained from a specific place, and it cannot be exchanged for money. The value of the gift card also counts towards the 100 euro limit. If the conditions are not met, for example if the gift is given as money, the gift is taxable pay for the employee.
The company can deduct the cost of staff gifts in income taxation, because they are not entertainment expenses. VAT on staff gifts is not deducted: according to the Tax Administration's VAT guidance, goods given to staff are not regarded as ordinary promotional gifts. If staff receive the same logo products free of charge as customers, own-use VAT is payable on the transfer according to the guidance.
The guidance does not say whether VAT is included in the 100 euro limit, so it is safest to calculate the limit from the price including VAT. The prices on the site are excluding VAT. At the general VAT rate of 25.5 per cent, 100 euros including VAT is 79.68 euros excluding VAT.
The rules and examples are explained in more detail in the article Taxation of corporate gifts (Liikelahjojen verotus).
Milestone occasions
An employee's milestone gift has its own value limit: a reasonable value for the gift is no more than the equivalent of one to two weeks of the employee's gross pay. For example, with a monthly salary of 4,000 euros, one week's gross pay is about 920 euros. Customary milestone occasions include 40th, 50th and 60th birthdays, at least 10 years of service, and retirement. A gift given on a 65th birthday, on the other hand, has not been accepted as tax-free in case law.
The conditions are that the employer chooses the gift, the gift is not money, and remembering milestone occasions is a practice that applies to the whole staff.
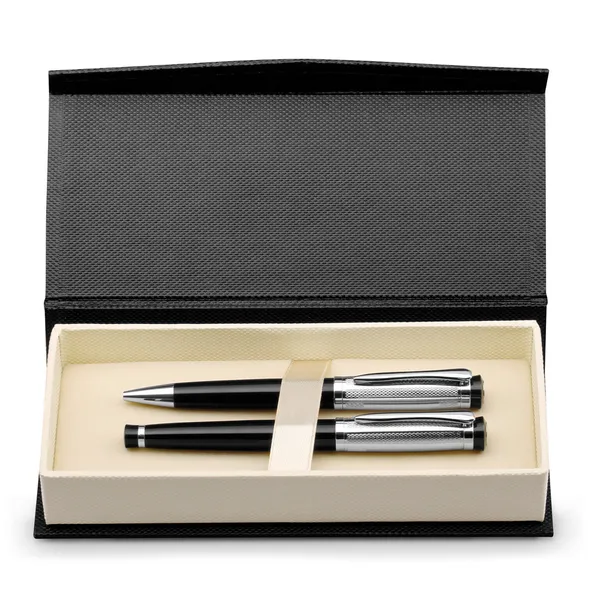
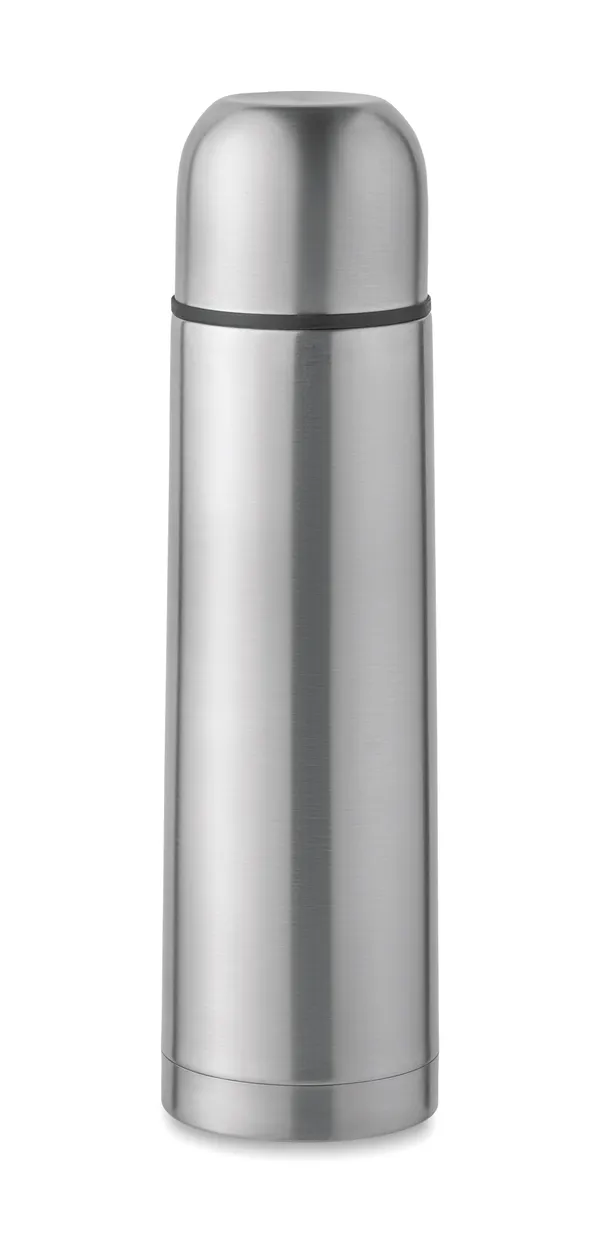
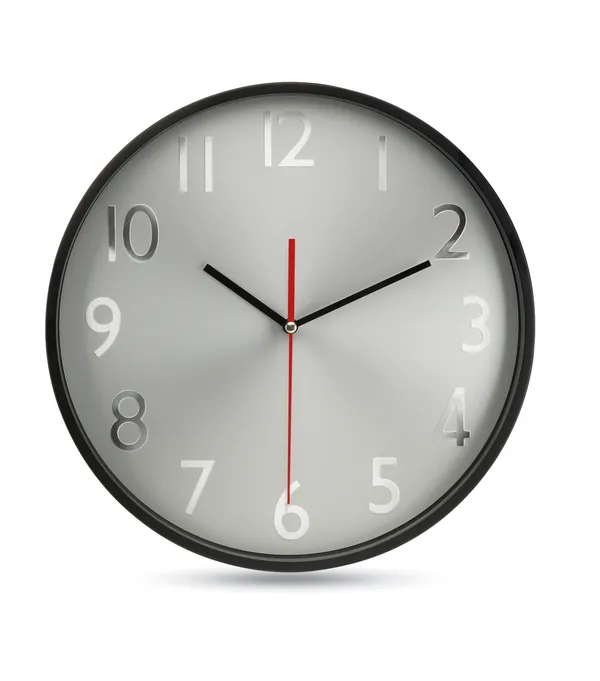
Of the products that can be printed with a logo, pen sets, blankets, thermos flasks and wall clocks, for example, suit a milestone gift.
Christmas
A Christmas gift is a typical minor gift, and the conditions described above apply to it. Gift ideas for staff and customers can be found on the page Christmas gifts for companies (Joululahjat yrityksille).
New employee
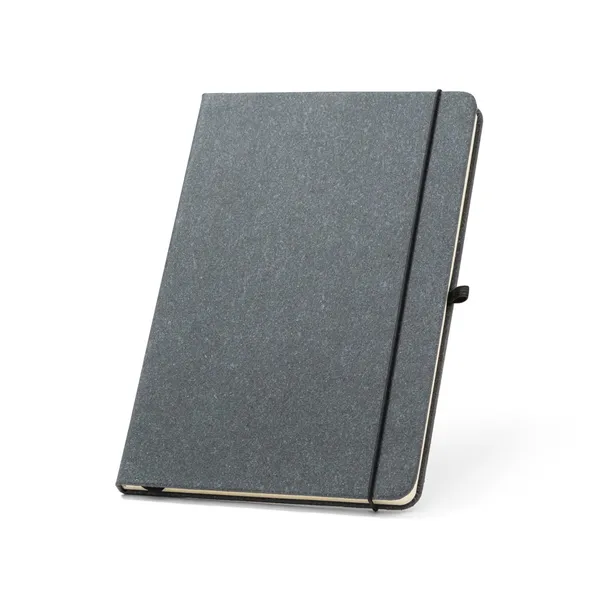
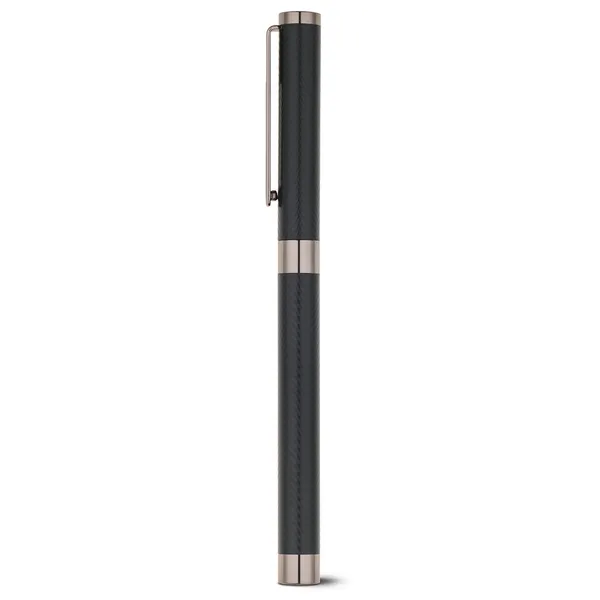
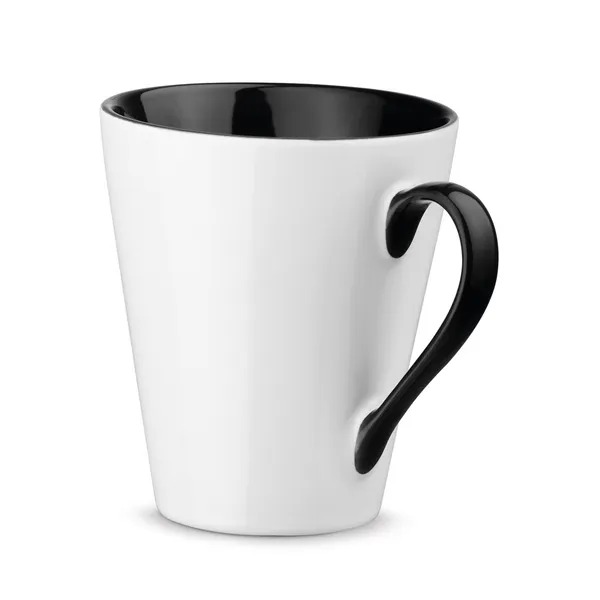
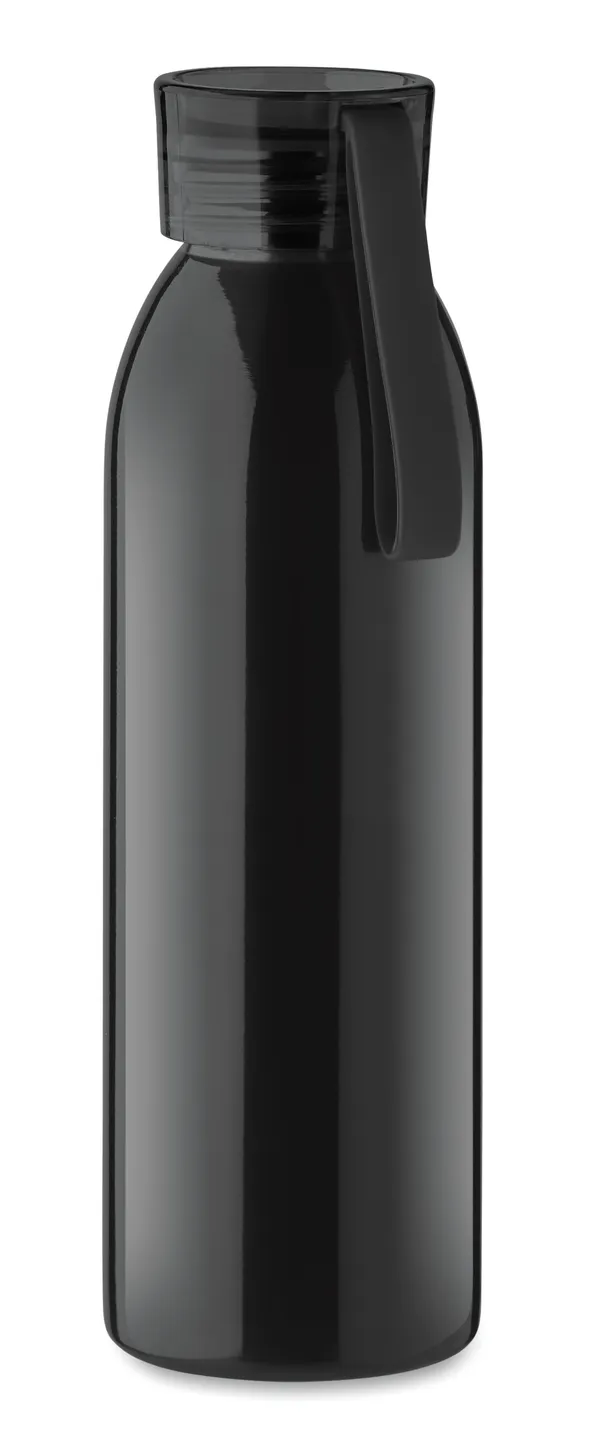
Products used at work and in everyday life suit a welcome pack for a new employee, for example a notebook, a ballpoint pen, a mug or a water bottle, a cotton bag and a hoodie.
If new employees start a few at a time, choose products that can be ordered in small quantities. Some of the hoodies, sweatshirts and cotton bags can be ordered from 10 pieces. For most other products the minimum order quantity is 50 pieces, and it is shown on the product page. All the products in the pack can be put into the same quote request.
Summer party and recreation day
Products used outdoors suit a summer party and a recreation day, such as beach accessories, sunglasses, outdoor games and cooler bags. Beach accessories include, for example, beach towels, beach balls and parasols.
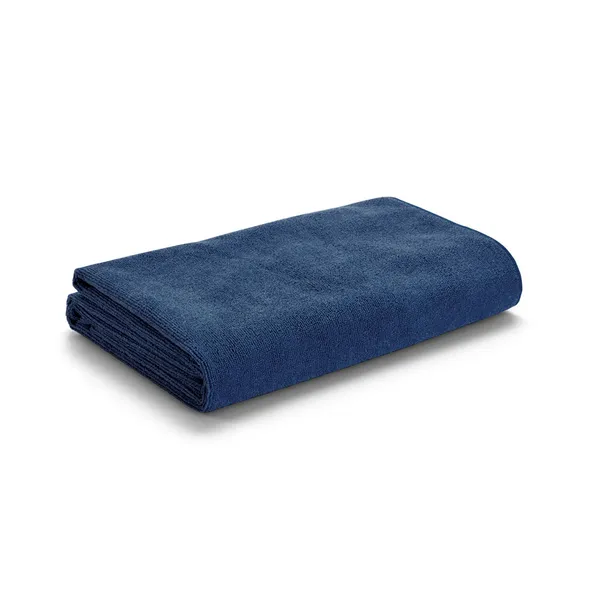
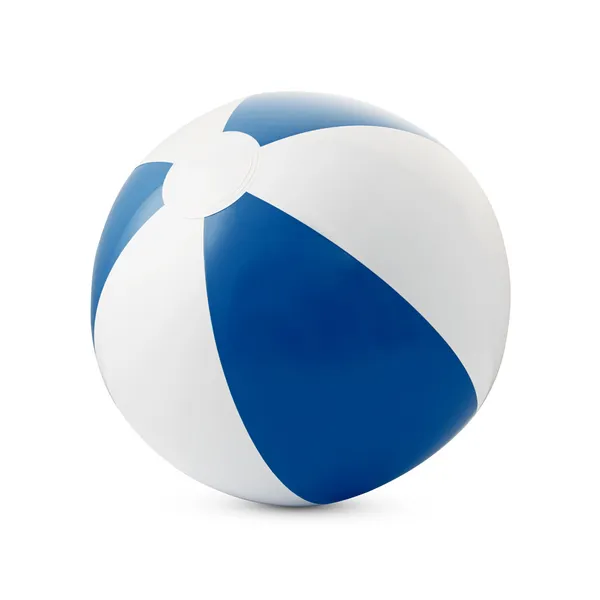
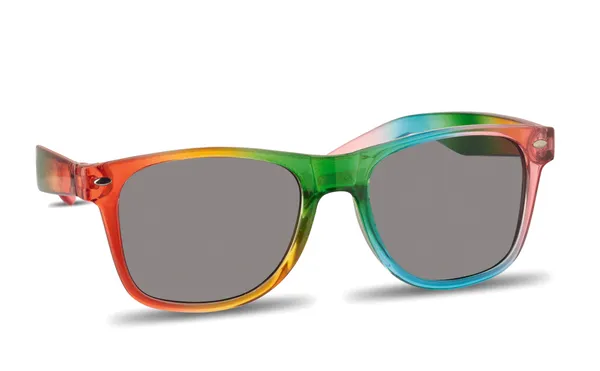
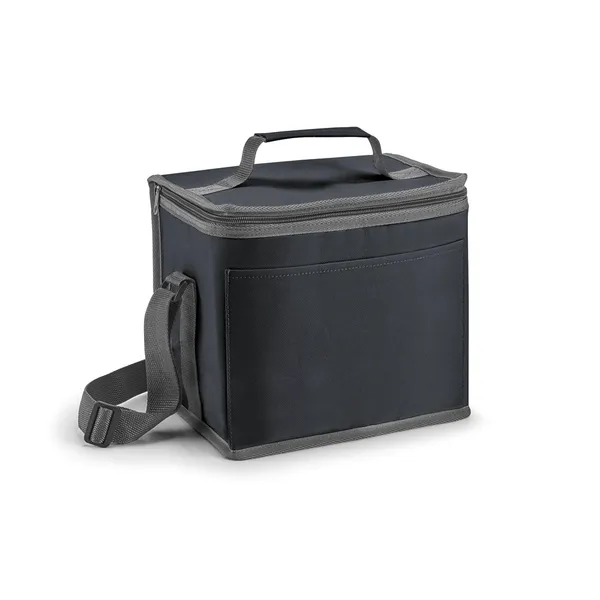
A summer gift counts towards the same 100 euro annual limit as a Christmas gift if the staff receive both in the same year.
How to order
Add the gift products to the quote basket and send a quote request. In the request, state the quantities and colours, for clothing the size breakdown, and what is to be printed on the products. You will receive a quote within one working day, and the request does not oblige you to order.
Before production you will receive a print proof for approval. Production starts when the proof has been approved. The exact lead time is stated in the quote. State the delivery date you want in the quote request.
The ordering steps are described on the page How to order (Näin tilaat).
Frequently asked questions
Can VAT be deducted on staff gifts?
No. Goods given to staff are not regarded as ordinary promotional gifts, so VAT on them is not deducted. The cost of the gifts can, however, be deducted in income taxation.
How are staff gifts treated in taxation?
A minor gift is tax-free for the employee when it is given to the whole staff, it is not money, and the total value of the gifts is no more than 100 euros a year. The value of a milestone gift can be higher. For the company, the cost of the gifts is deductible.
Can an employee choose their own gift?
Yes, if the employer has decided the options in advance. According to the guidance, choosing from predefined options does not make the gift taxable.